Buying guide
Brightline test explained
Everything you need to know about New Zealand’s capital gains tax

AI summary
New Zealand's brightline test taxes profits from selling residential property within two years. This profit is added to your income and taxed at your marginal rate. As of July 1, 2024, the two-year rule applies to all properties regardless of when they were purchased.
Key exemptions include your main home, inherited property, and relationship property settlements. However, the main home exemption has conditions and may not apply if you have a pattern of buying and selling for profit.
To ensure compliance, it is recommended to consult a tax accountant before selling.
What is the brightline test?
Why the NZ brightline tax was introduced
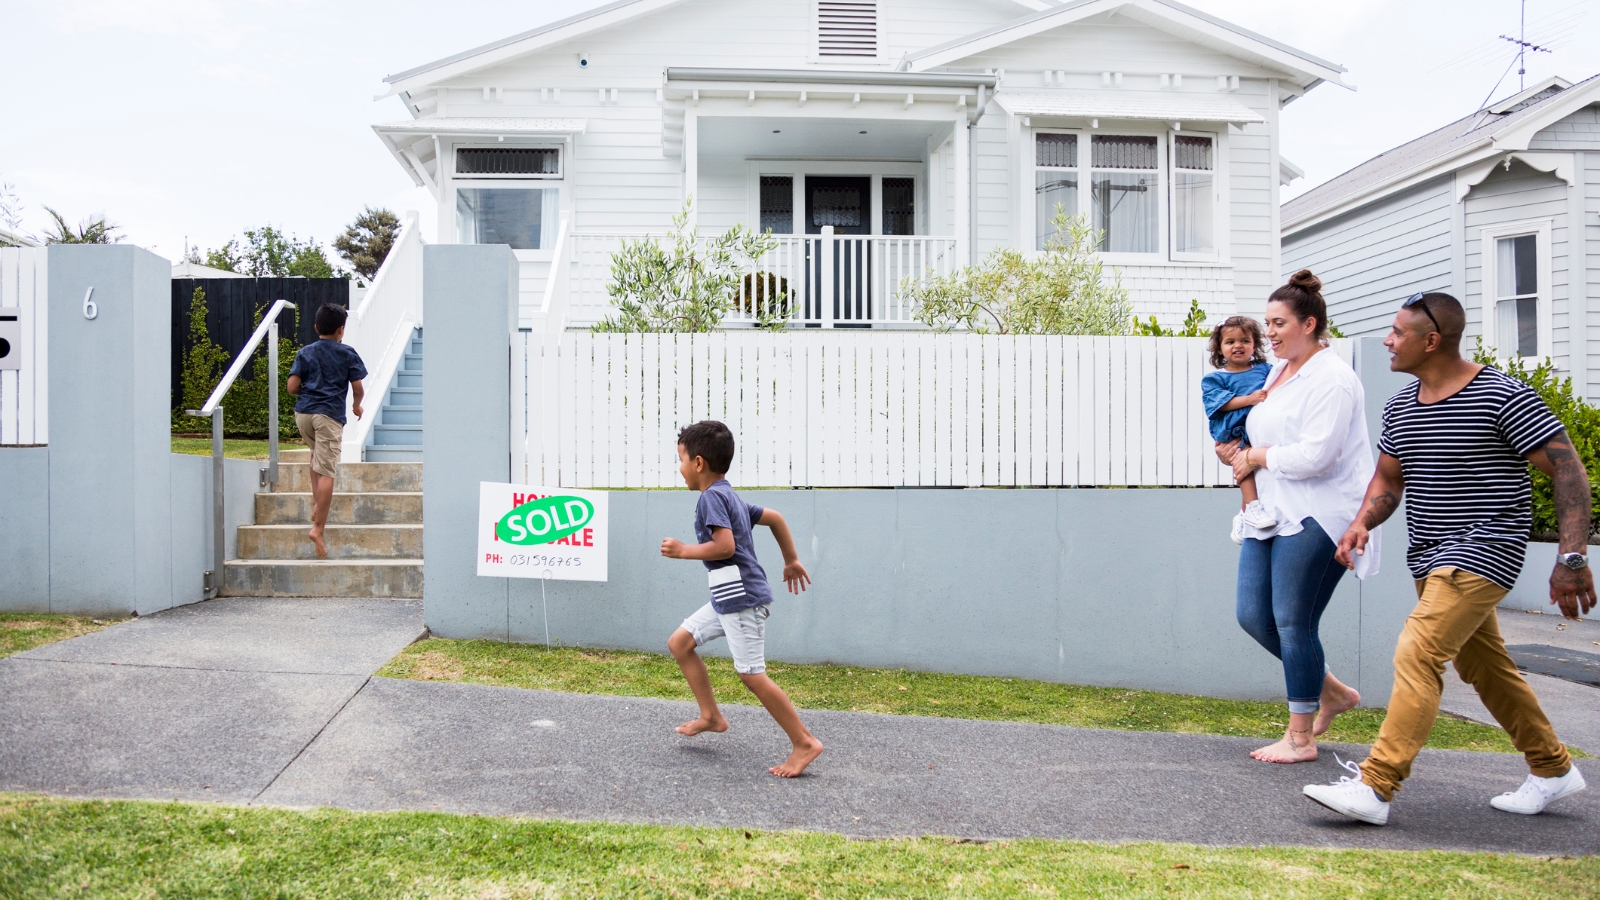
The family home is usually not covered by the brightline, unless it's been rented out.
Exceptions to the brightline test
Your main home
Inherited real estate
Relationship property
Your capital gains may be taxed if:
You’re in a pattern of buying and selling property for profit
You’re a builder or property developer
You’ve rented out your main home
The bigger the gain, the higher the tax.
You’ve sold the property to an entity
How to work out how much you’ll be taxed
Get expert advice from a tax accountant
Author
Discover More
The 1900s villa charmed them from the front, but it was what lay beyond the back door that sealed the deal
The 1900s Newtown villa has character, history and a rare backyard that became a family favourite.
Quirky and colourful: ‘It’s almost like stepping into Alice in Wonderland’
This colourful Kelburn home has quirky architecture, three levels, city views and a much-loved history.


Search
Other articles you might like