Buying guide
Brightline test explained
Everything you need to know about New Zealand’s capital gains tax

AI summary
The brightline test taxes profits from selling residential property within two years. As of July 2024, this two-year period applies to all properties, with the gain taxed at your marginal income tax rate.
Your main home is the primary exemption, though conditions apply. Inherited property and relationship property settlements are also typically exempt from the test.
The tax is calculated on your net profit after deducting expenses like legal and agent fees. Due to its complexity, seeking professional advice from a tax accountant is recommended.
What is the brightline test?
Why the NZ brightline tax was introduced
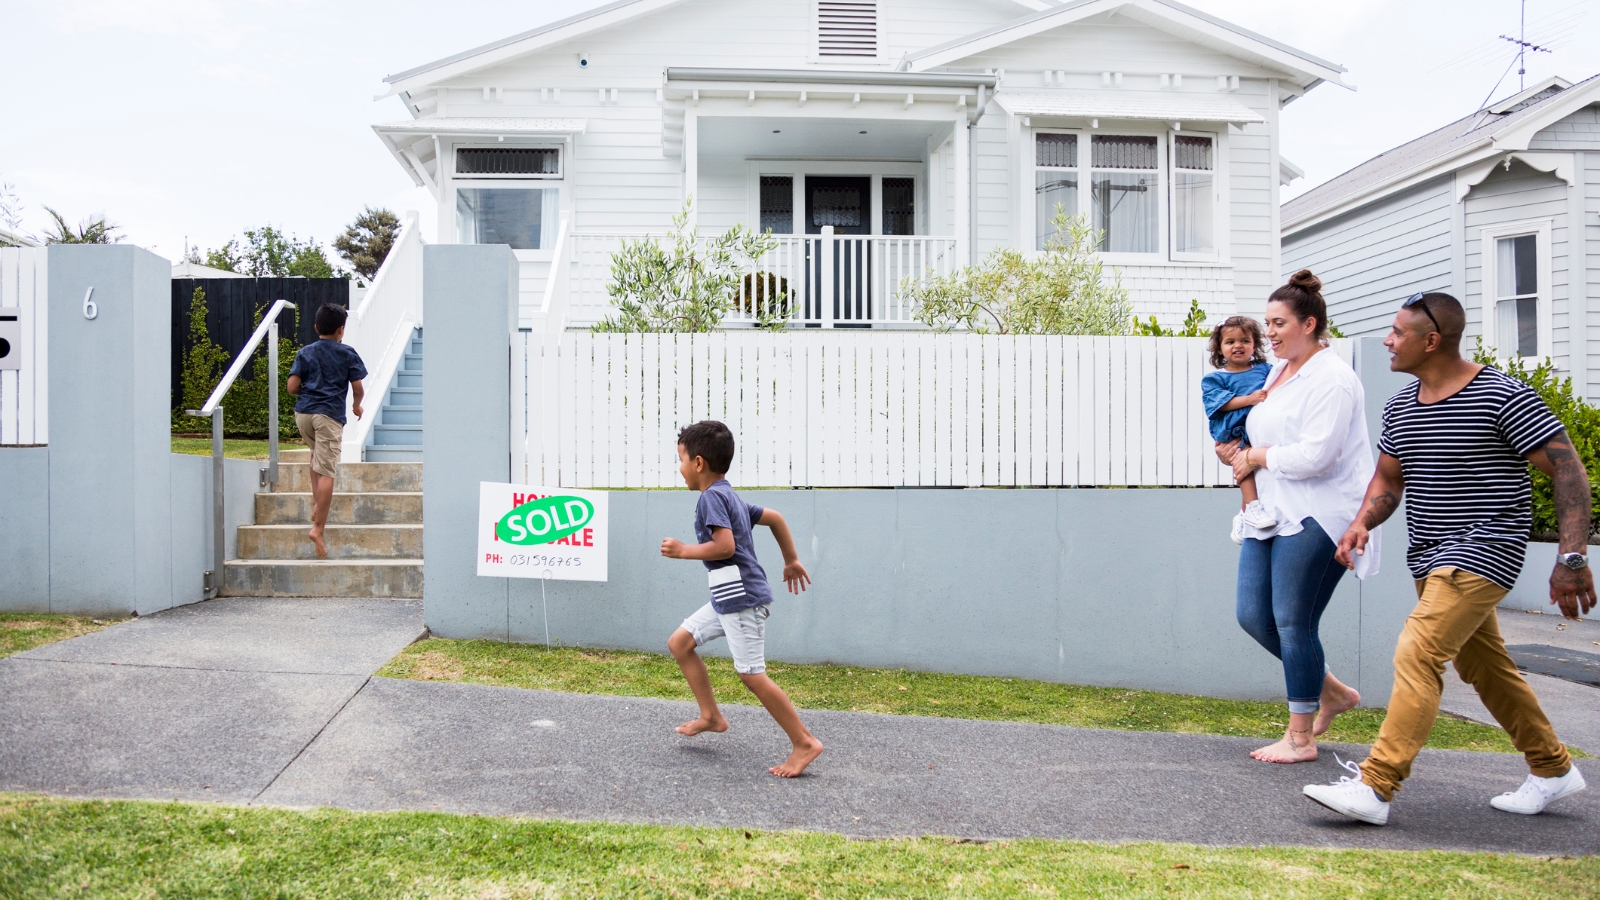
The family home is usually not covered by the brightline, unless it's been rented out.
Exceptions to the brightline test
Your main home
Inherited real estate
Relationship property
Your capital gains may be taxed if:
You’re in a pattern of buying and selling property for profit
You’re a builder or property developer
You’ve rented out your main home
The bigger the gain, the higher the tax.
You’ve sold the property to an entity
How to work out how much you’ll be taxed
Get expert advice from a tax accountant
Author
Discover More
‘We’ve loved the fact that it’s unconventional and quirky’
A character-filled 1950s Mangawhai bach with sleep-outs and a caravan is heading to market.
Rare 1980s architectural gem with lush gardens for sale in Te Puke
A distinctive Te Puke home with lush gardens and a 32-year family history is on the market.


Search
Other articles you might like