Buying guide
Getting a mortgage if you’re self-employed
Experts explain why it can be more difficult to get a mortgage if you're self-employed.

AI summary
Getting a mortgage when self-employed can be challenging as banks require at least one year of financial records. Claiming business expenses often reduces your on-paper income, which can limit your borrowing power.
Non-bank lenders like Resimac offer a more flexible, "common sense" approach. They may accept alternative income verification, such as business bank statements or an accountant's letter. While initial interest rates might be slightly higher, this provides a viable path to homeownership for contractors and business owners.
What you’ll learn:
What mortgage advisers say about options for self-employed
Taking the alternate lender route
Q & A with Luke Jackson, General Manager of Resimac NZ
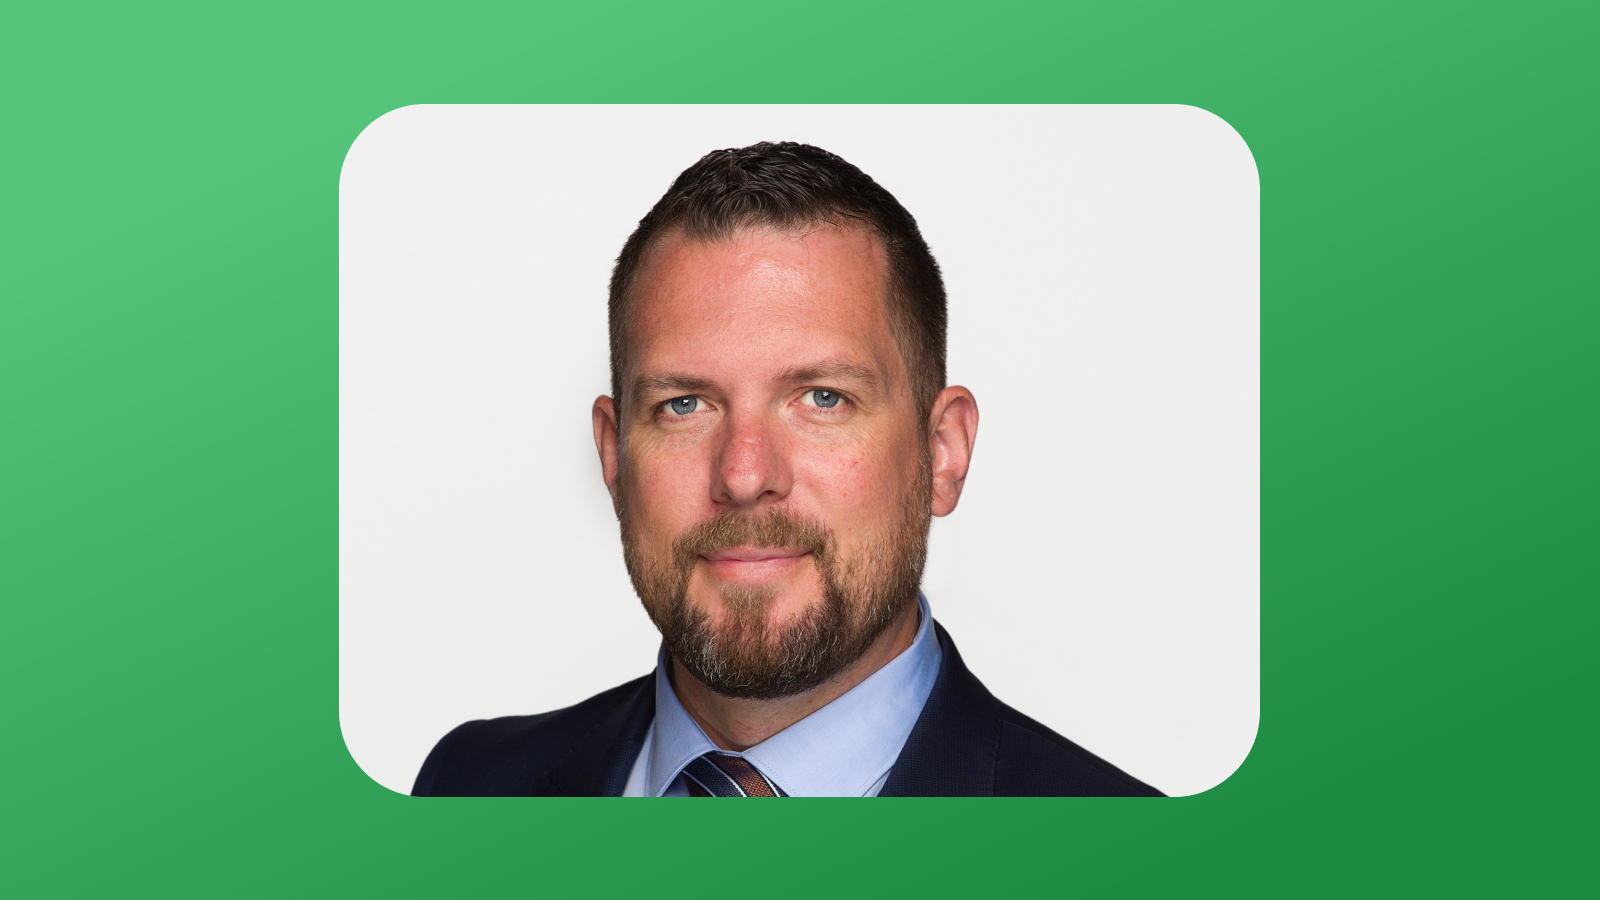
Luke Resimac anwers questions on lending for the self employed
Will more lenders be catering to self-employed people as they become a bigger part of the workforce?
How do you assess a self-employed borrower?
Are mortgage rates higher for self-employed people?
Would you be more confident about a loan if, in a couple, one of the borrowers was on a salary and the other was self-employed?
Any other pieces of advice for self-employed home buyers?
Author
Discover More

First home buyer stories: from casual browsing to owning a hidden gem in Onehunga
Today's buyer-friendly environment is turning long-held real estate dreams into reality. Just ask Diana Ahumada.
First home buyer stories: From an empty auction room to One Tree Hill
A ghost auction, maxed-out KiwiSaver, and a builder uncle's nod: how Zach and Zara bought their first home.


Search
Other articles you might like


