Buying guide
Home insurance in NZ: A simple guide
Understand your cover, avoid the pitfalls, and protect your place.
5 November 2025


AI summary
Protecting your home in NZ involves two layers: your private policy and Natural Hazards Cover from Toka Tū Ake – NHC. Most insurers use a sum insured model, the maximum rebuild cost that you must set. It's crucial to calculate this figure accurately to avoid being underinsured.
Your sum insured should include demolition, professional fees, and other structures like fences. Review this amount regularly. When choosing a policy, compare options, check financial strength ratings, and bundle for discounts.
What you’ll learn
House vs contents insurance: A quick clarification
What is and isn’t typically covered
Typically covered:
Common exclusions:
How much should you insure your house for?
What is sum insured?
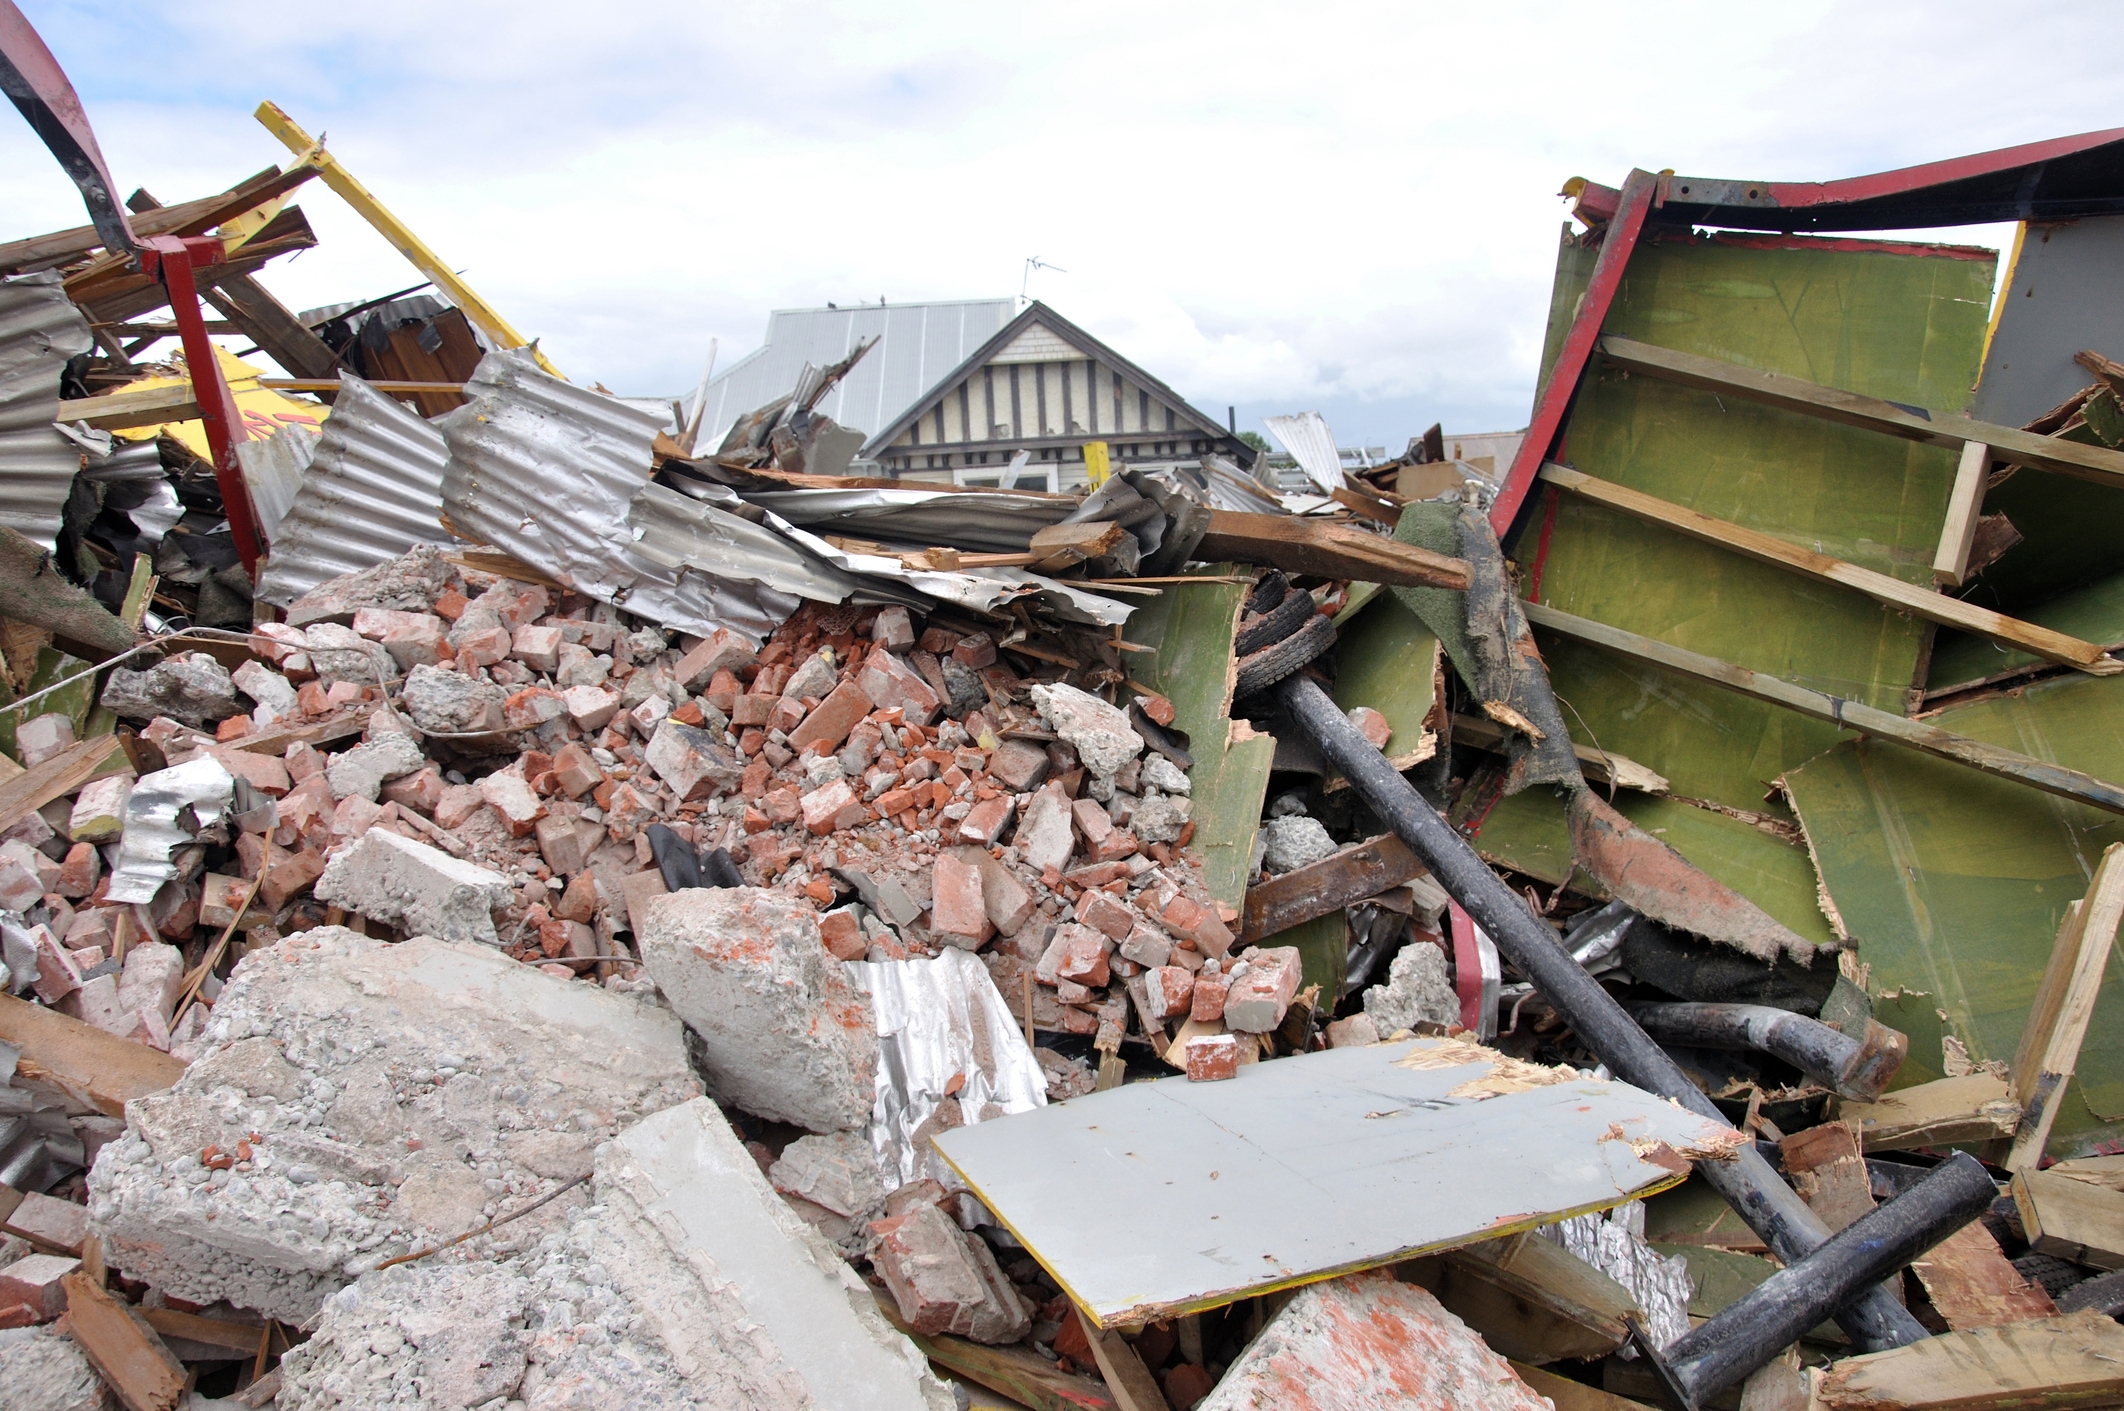
Insurers changed their cover models following the Christchurch earthquakes.
Why insurers switched to the ‘Sum Insured’ model
Alternative models
Where does Natural Hazards Cover fit in?
Comparing home insurance options
Choosing the best house insurance provider
House Insurance NZ – FAQs
What is an excess in house insurance?
What is a financial strength rating?
Why are my house insurance premiums going up?
Does house insurance cover natural disasters in NZ?
Is my house covered while being renovated?
Can I get a discount for bundling policies?
What’s the difference between replacement value and market value?
Author
Discover More
‘God’s work’: From earthquake-damaged church to social housing, and the 1880s villa given new life
The Here Awards honour an 1880s villa renovation and a Christchurch church transformed into social housing.
Historic Tūrangi home built for Italian tunnelling director hits the market
A 1960s Tūrangi home linked to the Tongariro Power Scheme is on the market for $765,000.


Search
Other articles you might like


