Buying guide
Buying off the plan: 15 things you need to know
Looking at buying off the plan? Here’s everything you need to know to ensure your purchase goes smoothly.

AI summary
Buying off the plan means purchasing a property from a developer before construction is finished. This allows you to secure a brand new home, built to the latest code, and potentially lock in a price that could increase by completion.
Before committing, it's crucial to research the developer's reputation and get legal advice on the contract, especially the 'sunset clause' for delays. Investigate the location, body corporate rules, and secure finance pre-approval, noting it will be reassessed later.
What does buying off the plan mean?
Benefits of buying off the plan
What to know before buying off the plan
1. Do your homework on the developer
2. Consider liveability
3. Look at the location
4. Research market movements
5. Know what happens if there are construction delays
Buying an apartment off the plan can be a great investment.
6. Seek legal advice
7. Look into the body corporate
8. Check your eligibility for government support
9. Consider your finance
10. Ask about security
11. Check the soundproofing
12. Understand the property’s outlook
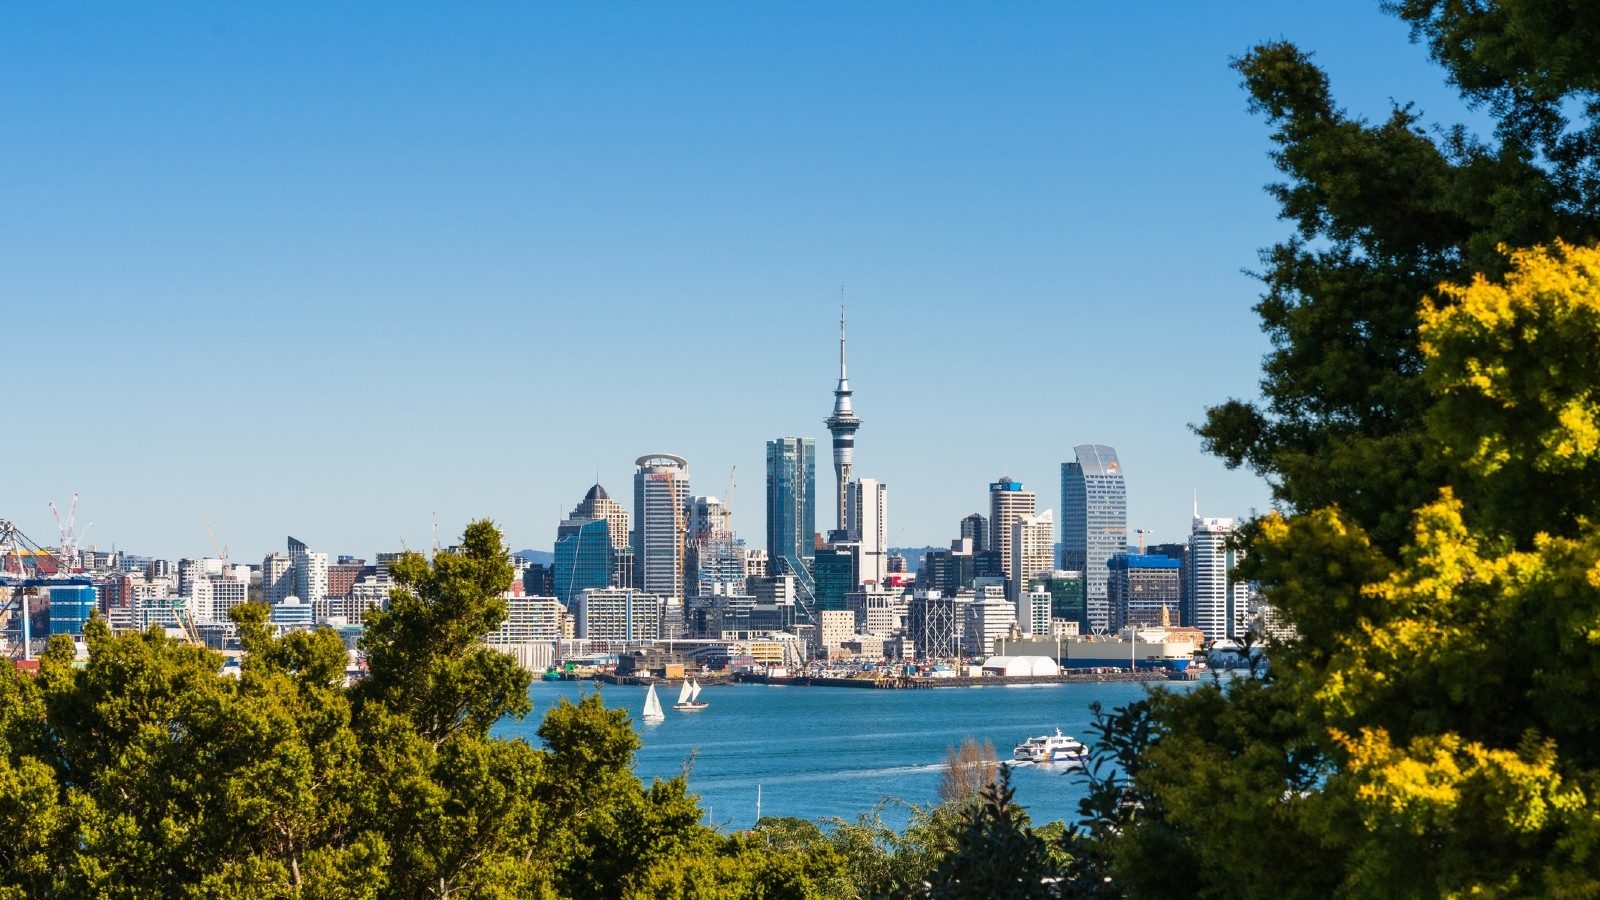
Make sure your apartment's outlook won't be built out before you buy.
13. Think about resale and appeal
14. Understand the development site
15. Seek independent advice
Author
Discover More
'Most people haven't built enough garages for all their toys': Inside the Pauanui Waterways home with its own helipad
The son of a Pauanui founder built this Waterways home with its own helipad. After 26 years, it’s for sale.
Thinking about buying your first home? Here's how young Kiwi are making it happen
Most young Kiwi still plan to buy. Our research shows how they're funding it and what they'll trade to get there.


Search
Other articles you might like


